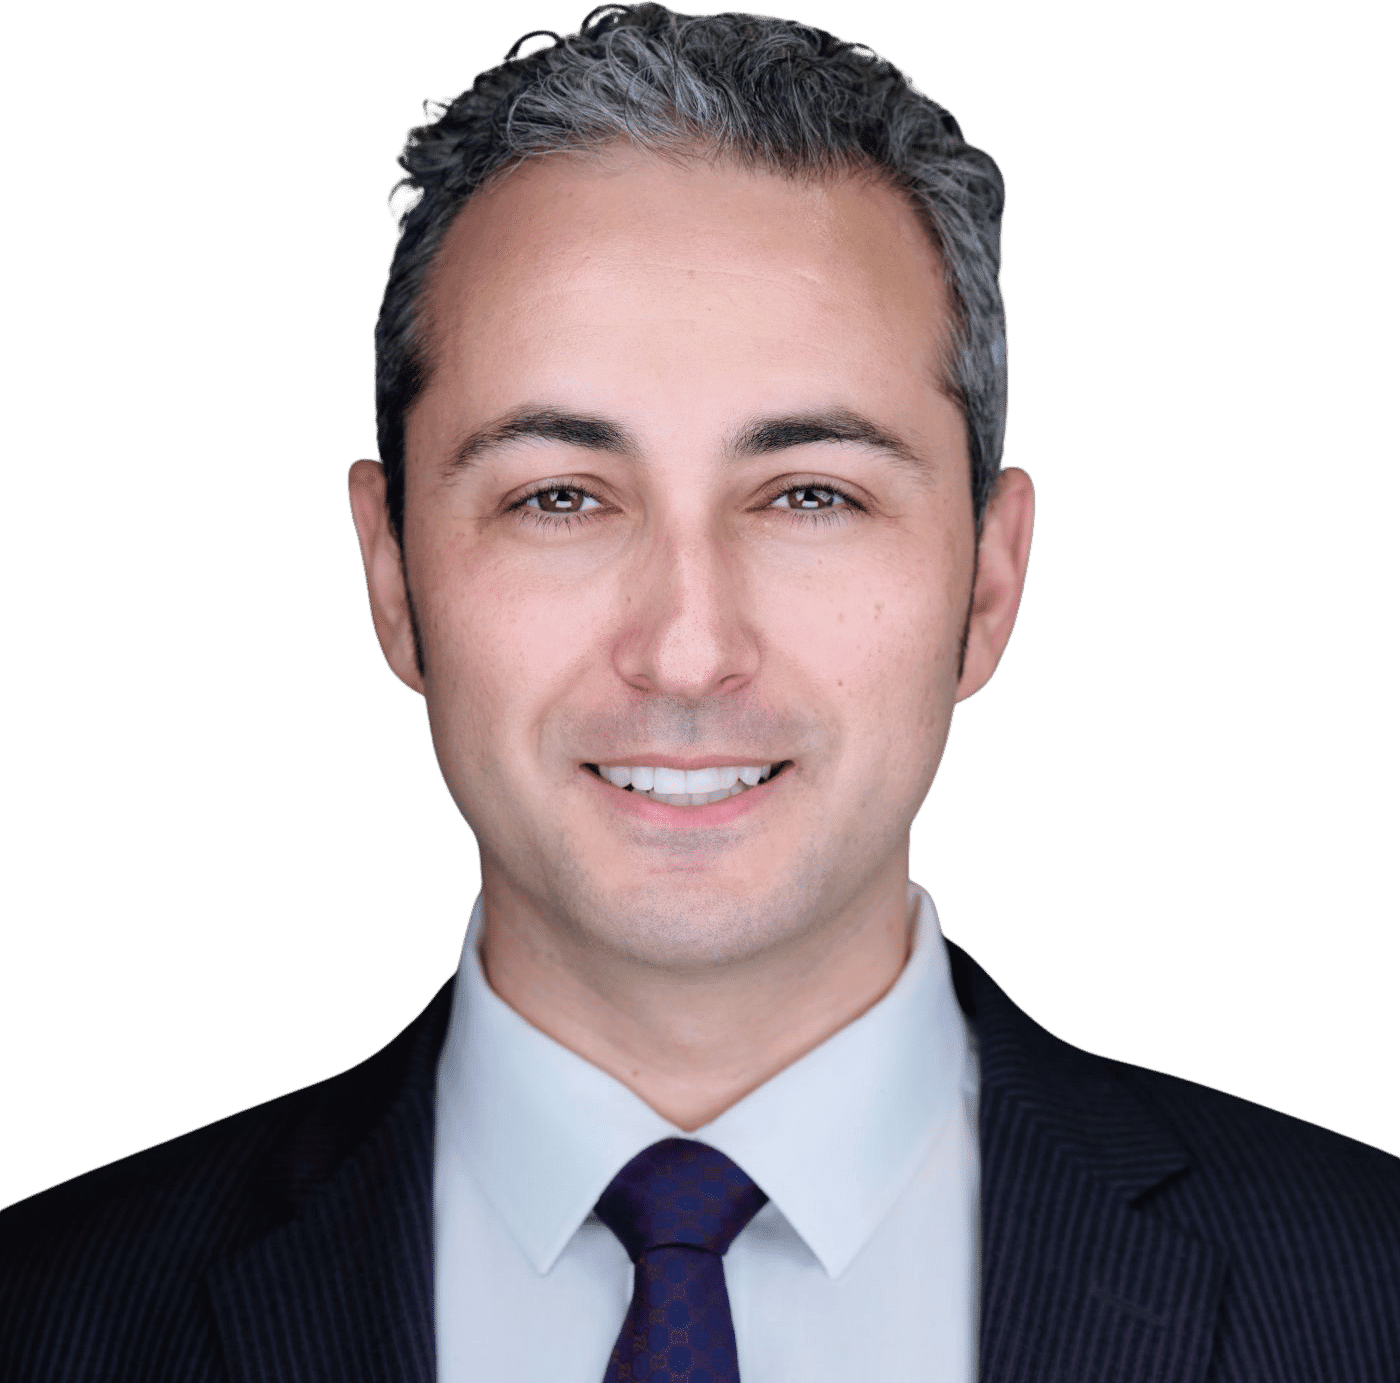
Reviewed by Larry Forman, Attorney
Weeks go by. The adjuster doesn't call back, or calls only to ask for something you already sent. It's one of the most common questions we hear: why is the insurance company taking so long? Some delay is normal in an injury claim, and some of it is a tactic. Kentucky law sets deadlines insurers have to meet, and knowing them helps you tell the difference.
Why is the insurance company taking so long?
Some reasons are legitimate:
- You're still treating. No one can value an injury claim until doctors know how serious it is. Settling early can leave future care unpaid.
- Records and bills take time. Hospitals, imaging centers and therapists each produce their own records. See how to request your medical records.
- Liens have to be sorted out. Health plans, Medicare, Medicaid and providers may claim part of the settlement. See medical liens in a Kentucky injury settlement.
- More than one policy is involved. PIP, the at-fault driver's liability coverage and your uninsured or underinsured motorist coverage may all play a part, and each insurer has its own process.
- Fault is disputed. The insurer may be waiting on the police report, witness statements or vehicle data.
Others aren't:
- Unreturned calls and emails
- Repeated requests for documents you already provided
- "The file is under review" for months, with no specific question
- A file passed from adjuster to adjuster
- Waiting you out until you need money badly enough to take a low offer
Our guide to insurance adjuster tactics covers more of the second kind.
What deadlines do Kentucky insurers have to meet?
Kentucky's unfair claims settlement regulation for property and casualty insurers, 806 KAR 12:095, sets response clocks. Some apply to every claimant; others apply only to claims under your own policy ("first-party" claims such as PIP, collision, or uninsured and underinsured motorist coverage).
| Rule | Deadline | Applies to | Source |
|---|---|---|---|
| Acknowledge your claim | 15 business days after notice, unless paid in that time | All claimants | 806 KAR 12:095 § 5(1) |
| Reply to your letters that call for a response | 15 business days | All claimants | § 5(3) |
| Offer payment due | 30 calendar days after proof of loss. Undisputed amounts must be paid within 30 days even if other parts are disputed | Your own insurer | § 6(1)(a) |
| Tell you why it needs more time to accept or deny | 30 calendar days after proof of loss | Your own insurer | § 6(1)(c) |
| Status letter with reasons for more time | 45 calendar days after notice, then every 45 days | Your own insurer | § 6(1)(d) |
| Affirm or deny liability | "Within a reasonable time." Pay within 30 days once liability is affirmed and the amount isn't disputed | All claimants, including claims against the at-fault driver's insurer | § 6(5) |
| Warn you about a time limit if you have no lawyer | Written notice at least 30 calendar days before it runs | Your own insurer | § 6(3) |
The regulation defines "days" as Monday through Friday, excluding holidays. Rules that say "calendar days" count every day.
PIP has its own timing rules
PIP benefits are generally overdue if not paid within 30 days after the insurer receives reasonable proof of the loss. Overdue benefits carry 12% interest a year, or 18% if the delay "was without reasonable foundation" (KRS 304.39-210). A court may also award attorney fees when overdue PIP benefits are recovered and the delay had no reasonable foundation (KRS 304.39-220). See how Kentucky PIP insurance works and Kentucky's 2026 PIP law changes.
Claims under your own policy
For claims under your own policy, KRS 304.12-235 generally requires payment within 30 days after the insurer gets notice and proof of claim in the form the policy requires. If the insurer doesn't make a good-faith attempt to settle in that time, the final settlement bears 12% interest. If the delay was without reasonable foundation, attorney fees may be reimbursed.
The deadline that doesn't wait for the insurer
Negotiating with an insurer doesn't stop the statute of limitations. For most Kentucky motor vehicle injury claims, you have two years from the injury or from the last PIP payment, whichever is later (KRS 304.39-230). If the at-fault driver's insurer is still "reviewing" as that date gets close, a lawsuit protects your claim while talks continue. See our statute of limitations guide.
What you can do when the insurance company is taking so long
- Put everything in writing. Follow up phone calls with a short email: what was discussed, what they asked for, what you sent and when.
- Send what's asked for once, and keep proof. Keep a log of every document and the date it went out.
- Ask a specific question. "What exactly do you need to make a decision, and by what date?" Under 806 KAR 12:095, a written question that calls for an answer should get a reply within 15 business days.
- Ask your own insurer for its status letter. For first-party claims, the insurer owes you written reasons when it needs more time.
- Escalate to a supervisor in writing if deadlines pass.
- File a complaint with the Kentucky Department of Insurance. Its Consumer Protection Division takes written complaints online at insurance.ky.gov, or by mail or fax. It doesn't accept complaints by phone.
- Talk to a lawyer if the delay is costing you treatment, income or time on the statute of limitations. If the insurer's conduct goes beyond a fair dispute, read about insurance bad faith.
What a fast settlement can cost you
The opposite problem is just as real. A quick offer before you've finished treatment usually doesn't account for future care, lost earning capacity or pain that lingers. Once you sign a release, you generally can't reopen the claim. See what affects a Kentucky injury case's value.
How Forman & Associates helps
We take over communication with every insurer, track their deadlines in writing, gather records and bills, sort out liens, and file suit when an insurer stalls toward the statute of limitations. When an insurer won't be fair, we're ready for court: Larry Forman has tried 50+ jury trials and won 95% of them. Learn more about our Louisville car accident practice.
Insurance company taking so long: FAQ
How long does an insurance company have to respond to a claim in Kentucky?
Under 806 KAR 12:095, an insurer generally must acknowledge a claim within 15 business days of notice and reply within 15 business days to letters that call for a response. On claims under your own policy, it must offer any payment due within 30 calendar days after proof of loss.
How long does PIP have to pay in Kentucky?
PIP benefits are generally overdue if not paid within 30 days after the insurer receives reasonable proof of the loss. Overdue benefits carry 12% interest, or 18% if the delay had no reasonable foundation.
Can I file a complaint about a slow insurance company?
Yes. The Kentucky Department of Insurance's Consumer Protection Division accepts written complaints online, by mail or by fax.
Does the statute of limitations stop while the insurer reviews my claim?
No. For most motor vehicle injury claims, the two-year deadline under KRS 304.39-230 keeps running during negotiations. Filing suit protects the claim.
Is it bad faith when an insurance company takes too long?
Not always. Some delay is normal. Kentucky's insurance code lists unfair practices, including failing to settle promptly when liability is reasonably clear. Whether a delay crosses that line depends on the facts.
Talk to a Louisville car accident lawyer
If the insurance company is taking so long that it's hurting you, call Forman & Associates Accident Injury Lawyers at (502) 931-6788 or get a free case evaluation. Our office is at 1139 S. 4th St., Louisville, KY 40203. No fee unless we win.
This post is general information about Kentucky law, not legal advice. Reviewed October 2026.